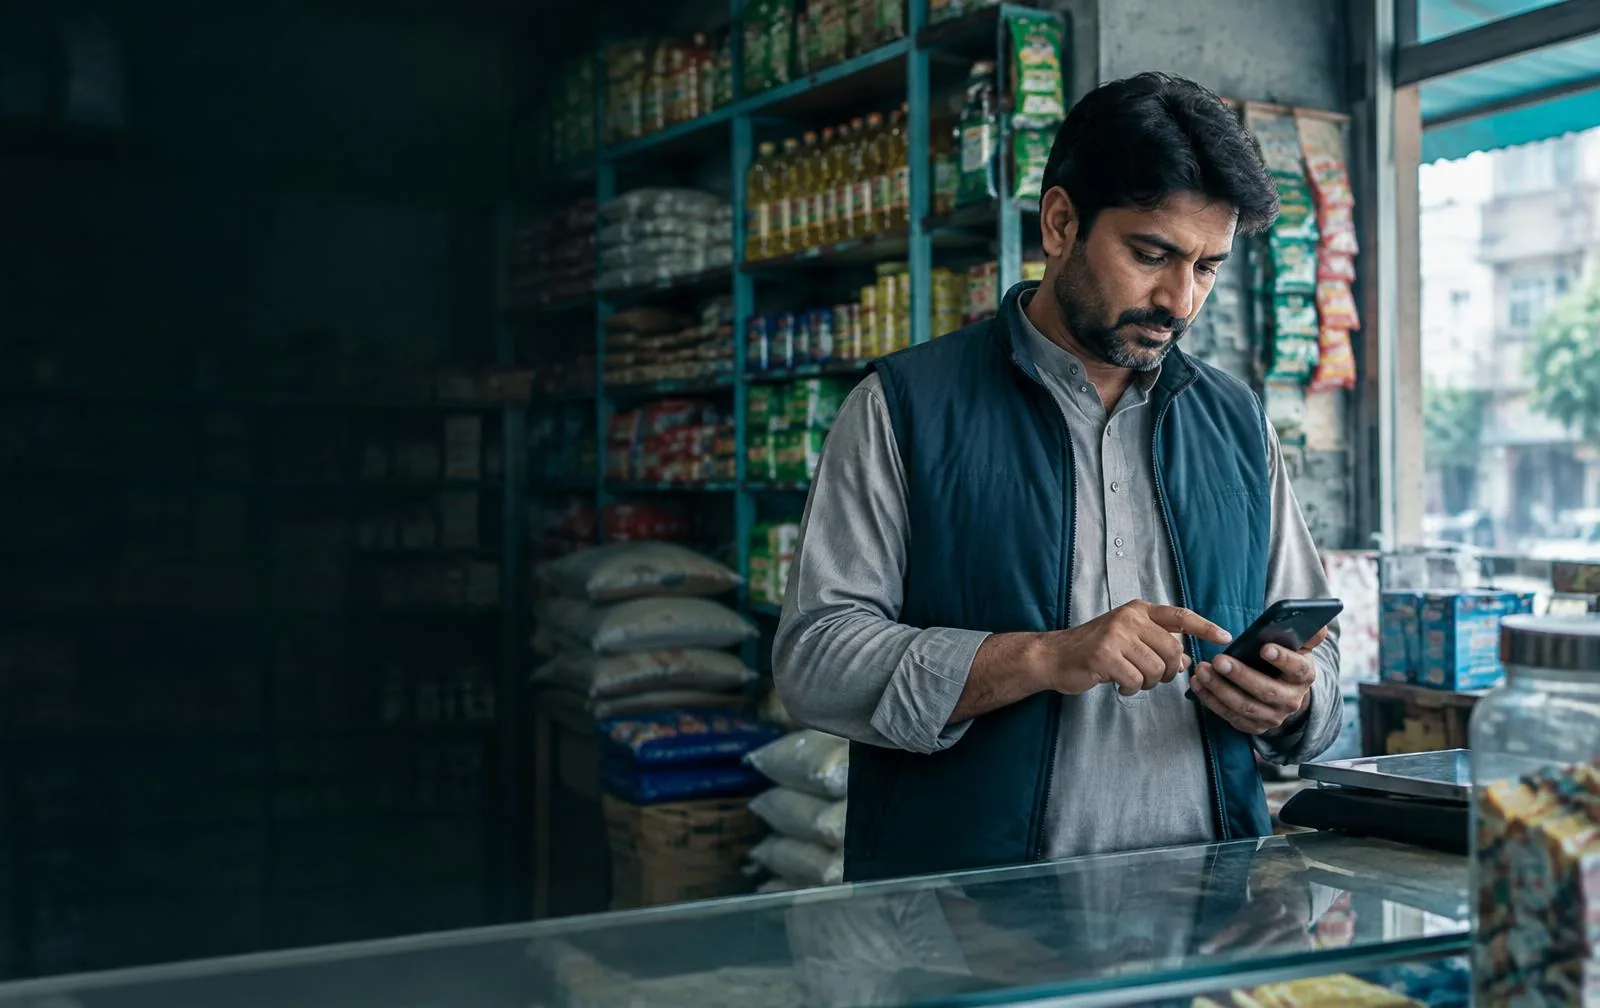
Picture a shop owner who has paid his phone bill on time for six years, receives steady payments through his wallet every week, and has never missed a utility payment. He applies for financing and is declined. Not because he is risky. Because the credit bureau has no file on him.
A missing credit file is not a missing financial history. The signal exists. It simply lives elsewhere. That blind spot can exclude reliable customers before a lender ever sees their real behavior.
02The Financing Paradox
More customer data. More demand. The same invisible borrowers. Traditional scoring depends heavily on a history with formal lenders. Without a loan or credit card, a first-time borrower may have little to show in a bureau file, even when years of reliable financial behavior exist elsewhere.
For Islamic banks, microfinance institutions and fintechs, this is more than a missed application. It is a blind spot in how creditworthiness is recognized.
03The Evidence Beyond the Bureau
Financial behavior leaves a trail. With appropriate consent, governance and local regulatory safeguards, lenders can consider signals already embedded in a customer's financial life.
01
Telco behavior
Top-up patterns, bill payments and consistent usage.
02
Transaction flows
How money actually moves in and out.
03
Device signals
Indicators of digital identity stability, used with care.
04
Open-banking data
Verified account activity, where available and authorized.
No single alternative signal proves someone can repay. Together, responsibly assessed, they can help lenders ask a better question than simply, 'Is there a file?'
04From Visibility to Action
Three capabilities make inclusive financing responsible. The next step is not simply a faster score. It is a better decision system, one that sees more, explains more and starts from the right foundation.
01
See the whole customer
Use relevant, permissioned alternative data to assess customers who are new to formal credit.
02
Explain every outcome
Give teams meaningful reasons, supporting evidence and an audit trail for each decision.
03
Design for Islamic finance
Build contract logic and governance into the platform instead of patching conventional lending workflows.
05Meet NeuroCredix
NeuroCredix is Neuronix's AI-enabled financing platform. It brings alternative-data assessment, embedded decisioning, explainable outcomes and Shariah-governed workflows into one operating environment.
Instead of asking customers to leave the moment and wait, NeuroCredix helps institutions bring responsible eligibility and decisioning closer to checkout, wallet and lending journeys.
06What Changes for Lenders
From 'no file' to a decision you can defend.
Access
Thin-file customers can be assessed through relevant, permissioned evidence instead of being invisible by default.
Speed
Eligibility and decisioning move closer to the customer's moment of intent without removing responsible controls.
Trust
Teams can see what drove an outcome, show the evidence and review every decision with a clear audit trail.
Integrity
Islamic financing principles are supported in the foundation, alongside the institution's own Shariah governance.
The Bottom Line
See the whole customer. Explain every decision. Better access begins with better visibility, and financial technology people can understand.